Market analysis · October 2026
The US housing market has a warning for Sydney. Just not the one you think.
America has more sellers than buyers and an affordability crisis. Sydney is showing similar symptoms. The causes are very different, and that difference decides what happens next.
There is a contradiction running through the American housing market. Buyers can’t afford to buy. Homes take longer to sell. In parts of the country sellers outnumber buyers, and builders are paying incentives to move stock. Yet American prices haven’t collapsed.
That contradiction sits at the centre of a widely shared US housing analysis doing the rounds this month. Its argument is simple. America isn’t having a conventional crash. It has a market where buyers struggle to buy, owners won’t sell, and prices hold up because supply in many places is still tight.
Sydney now has its own version of that tension. But the reasons are not the same, and the difference matters to anyone buying or selling in the Eastern Suburbs.
Where Sydney stands · October 2026
Part one · The US
What is happening in America
The striking point in the US analysis is that a market can have more sellers than buyers without prices falling over.
Cotality’s latest US figures show it. Single-family home prices were still 1.8% higher over the year to August 2026, even as buyers pulled back and affordability stayed stretched.
The 30-year lock-in
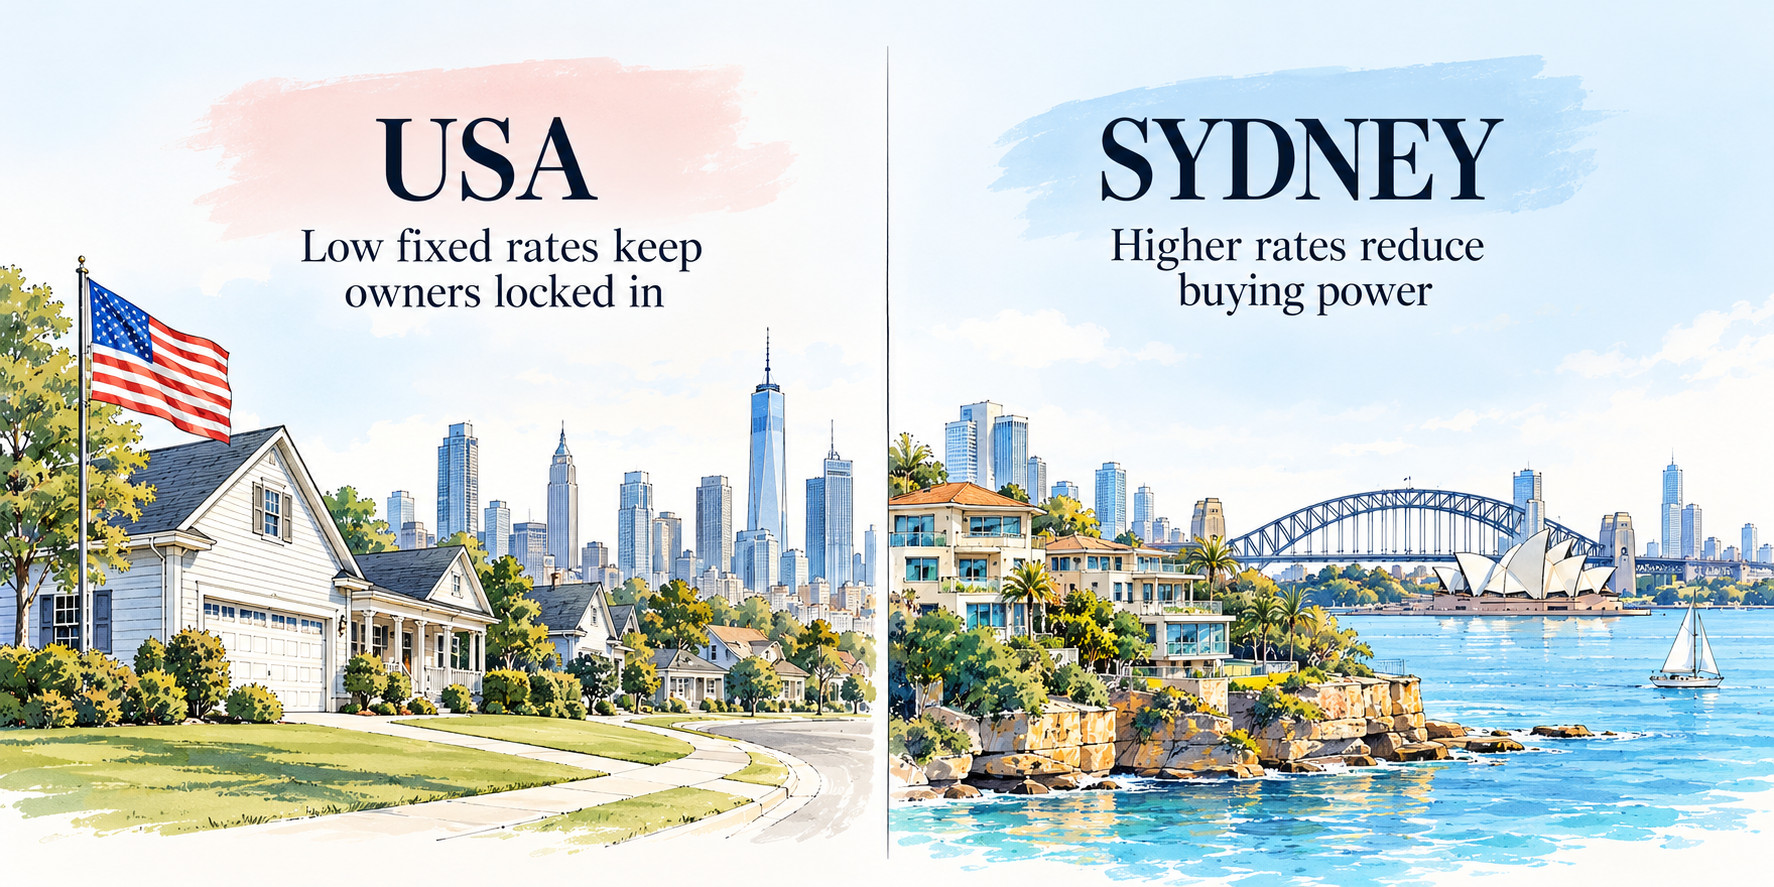
Part of the reason is structural. Millions of Americans locked in mortgages at very low rates during the pandemic, and US home loans are commonly fixed for 30 years.
An owner paying 3% has little reason to sell and finance the next home at 6% or 7%. So they stay put. That starves the resale market of stock.
It also means many owners who do test the market can afford to withdraw rather than cut their price. Economists increasingly call it a mobility problem, not a price problem.
Part two · The difference
Australia doesn’t have America’s lock-in
This is where the comparison needs care. Australian borrowers don’t have 30-year fixed loans.
The Reserve Bank says the share of outstanding Australian housing loans on fixed rates fell to a record low of under 5% in 2025. Almost every borrower is exposed to the cash rate.
Australia. Fewer than five in every hundred outstanding home loans were on a fixed rate in 2025, a record low. The rest reprice when the RBA moves.
United States. The 30-year fixed mortgage is the standard product. Owners who locked in low rates during the pandemic are shielded from today’s rates until they sell.
That makes Australia far more sensitive to monetary policy. When the RBA moves, existing borrowers feel it within weeks.
That’s exactly what happened. On 29 September the RBA lifted the cash rate by 0.25 percentage points to 4.60%, its fourth rise this year, after inflation came in stronger than it expected. The minutes of that meeting record the Board noting that housing prices had fallen by more than expected and that new home lending had dropped sharply, led by investors.
Cotality estimates the four rises since February have cut a median-income household’s borrowing capacity by almost $90,000, or about 9%.
American owners can shelter behind an old fixed mortgage. Australian borrowers can’t.
Part three · Sydney
Sydney is already adjusting
The Australian numbers are a good deal softer than the American headline. Cotality’s October Housing Chart Pack shows:
- National home values fell 1.1% in September, the sixth monthly fall in a row.
- National values are 5.2% below the March 2026 peak.
- Sydney recorded the largest quarterly fall of any capital, down 4.9% over the September quarter.
- Sydney values are 8.6% below their February peak.
- An estimated 39,747 homes sold nationally in September, 20.9% fewer than a year earlier.
- Total advertised stock is up 19.1% on last year, even though new listings are down 7.9%.
Read that combination carefully. Fewer homes are coming to market, yet stock is piling up, because buyers are taking far longer to commit. The median home now takes 41 days to sell, up from 26 a year ago.
The auction market tells the same story. In the week ending 11 October, just 45.6% of Sydney auctions cleared, against 68.2% in the same week last year.
The Eastern Suburbs held up better that week, clearing 57.9% of 57 auctions. One week proves nothing on its own. It is a reminder that a city-wide figure is an average of very different markets.
This isn’t a crash. But it is no longer the market where almost every well-located home drew a queue of aggressive bidders.
The premium end is feeling it most
This is where it gets relevant to the Eastern Suburbs. Cotality’s September Chart Pack found Sydney’s upper-quartile house values were 10.7% below their peak by the end of August, a much larger fall than in cheaper houses. Units have generally held up better, because a lower price opens them to a wider pool of buyers.
That doesn’t mean every expensive Eastern Suburbs home is down 10%. Markets don’t work that way. A renovated house in Bondi, a harbour-view apartment in Rose Bay, a development site in Bondi Junction and an older two-bedroom unit in Randwick can all move differently.
But the direction is clear. The higher the price, the smaller the buyer pool has become. When borrowing capacity falls, buyers get selective. And selective buyers do something boom-time buyers don’t.
They wait.
Part four · The imbalance
More stock. Not necessarily cheaper.
One of the sharper points in the US analysis is that a buyer’s market doesn’t automatically mean cheap homes. Australia is showing the same thing.
Advertised stock is up almost 20%. Sales are down around 21%. That hasn’t turned into fire sales. Capital-city vendors are now accepting a median 4.4% below their asking price to reach a contract. That is the most in five years, but a long way from distress.
Why? Most Australian owners aren’t forced sellers. Many simply decide that if they can’t get the price they want, they’ll wait. That’s especially true in established suburbs, where owners bought years or decades ago and hold substantial equity.
The result is an unusual market. Buyers have more negotiating power. Good homes can still be expensive.
Part five · Supply
Proposed supply isn’t completed housing
The US analysis makes another point. In parts of America, big builders can undercut established homes with mortgage-rate buy-downs, help with closing costs, free upgrades, smaller floorplans and incentives to clear stock. Private owners can’t match that financial engineering.
Sydney’s development market is different, but the lesson carries. There is a great deal of proposed supply in the NSW planning system.
As at 29 September, the Housing Delivery Authority pathway held 499 State Significant Development proposals with the potential for more than 154,000 homes. Only 24 had been approved, covering about 4,400 homes, and just 11 had started construction. Applications had been lodged for a further 75 projects, around 32,400 homes.
Proposed supply isn’t completed housing. And the construction pipeline is still difficult. In August, total dwelling approvals across Australia fell 6.1%, while approvals for apartments and other non-house dwellings fell 21.2% in the month.
Sydney needs more housing. But thousands of announced apartments won’t arrive on the market all at once.
Bondi Junction is a good example
Bondi Junction shows why property has to be read locally, not through national headlines. A substantial amount of apartment development is proposed around the centre over the coming years. In time, that will give buyers more choice.
But new apartments carry much higher land, construction and finishing costs than most existing stock. So the same suburb can have new supply on the way, softer prices in some established buildings, and very expensive new apartments, all at the same time.
That isn’t a contradiction. They are different products for different buyers. It’s why “Sydney prices are falling” tells you very little about what an individual apartment is worth. My building-by-building studies are in the Bondi Junction apartments guide.
Part six · First-home buyers
The desire hasn’t gone. The finance has.
The most concerning part of the American story is generational. In the US, getting into a first home increasingly depends on family wealth, with parents and relatives helping with deposits.
Australia faces a similar problem. In the June 2026 quarter there were 29,319 new owner-occupier first-home-buyer loans nationally, almost exactly the same number as a year earlier. But the value of those loans was 10% higher. The buyers who can get in are borrowing more to do it.
Those figures predate the September rate rise. The appetite to own hasn’t gone. The ability to finance it is now the constraint.
Part seven · Where the two markets split
Two homeowners. Two different problems.
America’s problem is largely mortgage lock-in. Sydney’s is more directly about borrowing capacity.
“I won’t sell, because I’d lose my 3% mortgage.”Locked in · Fewer homes come to market
“My repayments have gone up, and the buyer for my home can borrow less.”Exposed · Prices adjust to borrowing power
The outcome looks similar: fewer transactions. The economics underneath are quite different. Because Australian loans reprice quickly when the cash rate moves, Sydney prices respond to the RBA far faster than most US markets do.
Part eight · What to do
What this means for you
If you’re selling
Don’t price your home for the market that existed twelve months ago.There is still demand. There are still buyers with real capacity, and exceptional homes still draw competition.
But buyers now have more time, more listings to compare and more willingness to walk away. Presentation, marketing and above all pricing matter more than they have for years.
A home priced correctly can create competition. The same home priced 10% above where buyers see value can sit for weeks. The longer it sits, the stronger the buyer’s hand.
If you’re buying
You have something Sydney buyers haven’t had consistently for years: choice.That doesn’t make every property a bargain. It means you can compare.
- Read the strata records
- Study the previous sales
- Cost the renovation properly
- Weigh established apartments against new developments
And occasionally, say no. Sometimes the property you don’t buy saves you more than the one you negotiate well.
At a glance
The US argument, tested against Sydney
| The US argument | Sydney and Australia today | Applies here? |
|---|---|---|
| More sellers than buyers | Total listings up 19.1% while September sales fell 20.9% on a year earlier. | Strongly |
| Prices surprisingly resilient | Adjusting faster here. Sydney is 8.6% below its February peak. | Less so |
| Owners locked into cheap mortgages | Under 5% of Australian home loans are fixed. There is no 30-year lock-in. | Largely not |
| High rates freezing transactions | Cash rate at 4.60% after four rises in 2026. Borrowing capacity down about 9%. | Strongly |
| Builders using incentives | Less pronounced. New development competes differently with established stock. | Partly |
| More supply brings prices down | True in principle, but Sydney still struggles to turn approvals into completed homes. | Partly |
| First-home buyers squeezed | Loan numbers flat on a year ago, loan values up 10%. | Strongly |
| The market isn’t uniform | The Eastern Suburbs cleared 57.9% the week Sydney cleared 45.6%. | Strongly |
The view from here
Sydney is correcting. It isn’t America.
Australia should watch the United States closely. Both countries share the same underlying problem: housing has become very hard for younger households to afford.
But the two systems respond differently. America has owners trapped by cheap long-term mortgages. Australia has borrowers directly exposed to every rate move. Parts of America have built more homes than buyers want. Sydney still struggles to deliver enough finished homes in the places people most want to live.
That’s why I’d be very cautious about taking headlines predicting an American crash and applying them to Sydney.
Property is local. Sydney is dozens of markets, and even within the Eastern Suburbs, houses, older apartments, new developments and prestige homes can move in different directions at the same time.
After more than 35 years in Eastern Suburbs property, one principle hasn’t changed. The market sets the price. Not the owner, not the agent and not yesterday’s sale.
The advantage comes from understanding where that market is moving before everyone else does.
Selling or buying this season?
Get a straight read on your property.
A private, data-led conversation about where your home sits in this market, and how to price it to sell.
Sources
- Cotality, Monthly Housing Chart Pack, October 2026 (15 October 2026).
- Cotality, Home Value Index, September 2026 (1 October 2026).
- Cotality, Monthly Housing Chart Pack, September 2026 (10 September 2026).
- Cotality, Finalised clearance rates, week ending 11 October 2026.
- Cotality, RBA rate hike deepens housing market headwinds (29 September 2026).
- Cotality, US Home Price Insights, October 2026 (August 2026 data).
- Reserve Bank of Australia, Developments in Banks’ Funding Costs and Lending Rates, Bulletin, May 2026.
- Reserve Bank of Australia, Monetary Policy Board decision and minutes, September 2026.
- NSW Planning, More than 4,300 homes declared State Significant (29 September 2026).
- Australian Bureau of Statistics, Total dwelling approvals fall 6.1% in August (30 September 2026).
- Australian Bureau of Statistics, New home loans fall 5.4 per cent in June quarter (14 August 2026).
This article is general information only and does not take into account your personal circumstances. It is not financial, legal or lending advice. Figures are as published at 20 October 2026 and may be revised by their sources. Market commentary and outlook statements are the author’s professional opinion.